Home Depot Credit Card: Is It Worth Applying For in 2026?
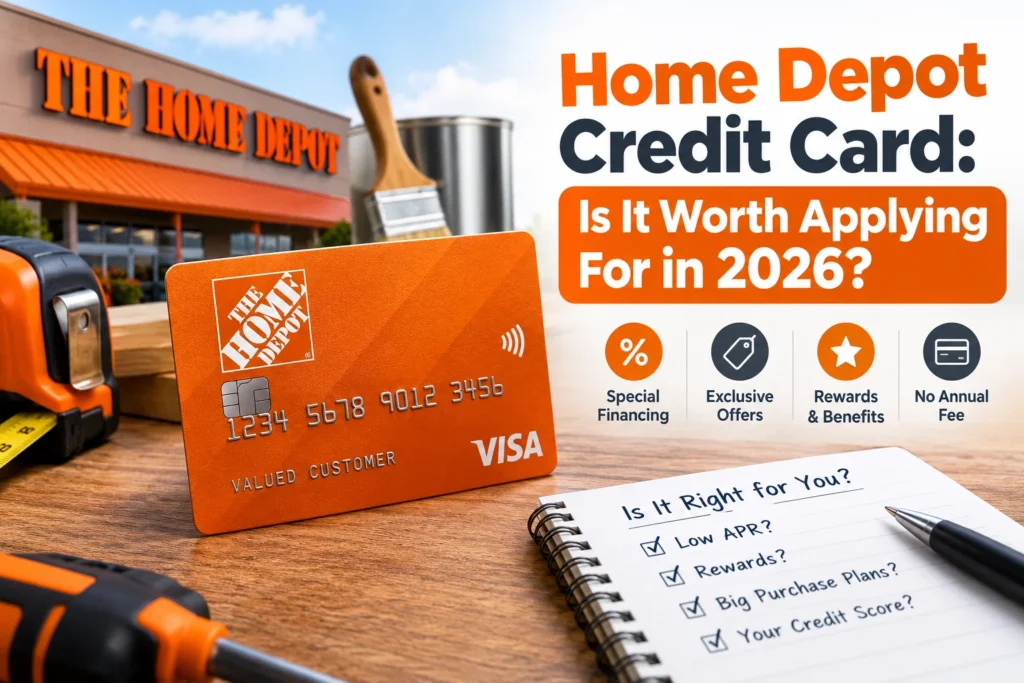
Is the Home Depot credit card worth it? For most people, only in one situation: you’re making a big purchase and you’re certain you can pay it off before the promo clock runs out. Outside of that, it’s a high-rate store card with nothing to earn.
I haven’t carried this card myself, so I won’t pretend otherwise. What follows comes from published terms and independent reviews, checked against consumer protection guidance.
What the Card Actually Offers
The Home Depot Consumer Credit Card is usable only at Home Depot stores and homedepot.com. Citibank is the issuer. There’s no annual fee, and the standard APR is 29.99%, which is variable. Late fees can reach $40.
The upsides are few but real:
- Six months with no interest on purchases of $299 or more, if you pay in full
- Longer terms, up to 24 months, during special promotions
- A one-year return window instead of three months
That return window is underrated. Ever bought flooring, then found out the shade looked wrong in your actual living room? A year gives you room to be wrong.
What’s missing? Rewards. The card is a financing tool, not a rewards earner. No points, no cash back, no daily discount.
The Catch: Deferred Interest
Here’s where people get burned. The “no interest” promo isn’t a true 0% offer. If you haven’t paid off the purchase by the time the promo ends, you owe interest dating back to the first day.
Quick math, mine, not the issuer’s. Put $2,500 on the card at 29.99% and pay nothing for six months, and the back-charged interest lands around $375. Pay all but $50, and you can still be charged interest on the full original amount. That’s the trap.
The CFPB has pushed on this. It noted that the costs of deferred interest typically show up only at the end of the promotional period, and it urged retailers to move toward 0% offers without back-charged interest. For cardholders, the agency’s advice is simple: know the promo length, know the post-promo rate, and know the monthly payment needed to clear the balance in time.
So don’t count on the minimum payment. Divide the purchase by the promo months, and pay at least that, ideally with autopay. Then aim to finish a month early.
Home Depot vs. Lowe’s Card
The rival card flips the deal. The Lowe’s card offers 5% off every day, or financing instead, but not both on the same purchase. Its purchase APR was 31.99% as of July 2026.
If you buy at one chain constantly and rarely finance, the discount card wins. If you’re funding a single big project, the Home Depot card’s longer return window and financing structure may suit you better. Neither is great for carrying a balance.
There’s also a third option. NerdWallet says a card with a true 0% intro APR lasting 12 months or longer is a better deal if you qualify. Those cards work anywhere, and interest doesn’t get back-charged.
Who Should Get It (and Who Shouldn’t)
It fits if you:
- Have a planned purchase of $299 or more, like an appliance or flooring
- Can pay it off inside the promo window without stress
- Shop at this retailer often enough to use the card for returns and promos
Skip it if you:
- Might carry a balance past the deadline
- Want rewards on everyday spending
- Shop around between stores
Honestly? If you’re unsure about paying on time, skip it. The downside is too steep.
How to Apply
- Check current offers. Promotions and new-account discounts change often. Confirm them on the retailer’s site before applying.
- Know the credit check. There’s no no-credit-check route; a hard inquiry is part of applying. The issuer doesn’t publish a minimum score, so I won’t guess one.
- Apply online or in store. You’ll need your income and identity details.
- Select the right financing term. One review warns that online purchases may default to a shorter window unless you pick the longer option at checkout.
- Mark your payoff date. Find it on your first statement, then set a calendar reminder.
FAQ: Home Depot Credit Card Questions
Q: Who issues it?
A: Citibank issues the Consumer Credit Card, per the card’s published terms.
Q: Is there an annual fee?
A: No. The cost comes from interest and late fees, not membership.
Q: Can I use it at other stores?
A: No. It works only at the retailer’s stores and website.
Q: Does it earn rewards?
A: No. Its value is financing and the extended return window.
Q: Is the “no interest” offer really 0% APR?
A: No. It’s deferred interest, so unpaid balances get charged interest from the purchase date.
Q: Will applying hurt my credit?
A: A hard inquiry can cause a small, temporary dip. It’s usually minor, but it’s there.